You are here
Feed aggregator
Kartoffelgratin mit Hackfleisch – ein rassiges Hauptgericht
Gschwellti kochen, Hackfleisch anbraten, Sauce drüber – ab in den Ofen! Im Handumdrehen ist dieser rassige Kartoffelgratin fertig und kann als leckeres Hauptgericht serviert werden. Zum Schluss verraten wir dir einen einfachen Trick, damit dein Gratin besonders knusprig wird.
Categories: Afrique, Swiss News
Retraite en Algérie depuis la France : conditions, cotisations et démarches CNAS
Les Algériens établis en France peuvent cotiser volontairement au système national de retraite en Algérie, à condition notamment d’avoir moins de 55 ans. Ce dispositif […]
L’article Retraite en Algérie depuis la France : conditions, cotisations et démarches CNAS est apparu en premier sur .
Categories: Afrique
South Africa's deputy police chief resigns after being charged with sexual offences
Shadrack Sibiya had denied grooming a 16-year-old and raping an 18-year-old.
Categories: Africa, Határon túli magyar portálok összesített hírei
Fausse employée d’une institution publique, elle escroque 8 personnes et soutire 800 millions
Une femme de 47 ans a été interpellée à Chlef puis déférée devant le parquet, soupçonnée d’avoir monté une vaste escroquerie fondée sur une fausse […]
L’article Fausse employée d’une institution publique, elle escroque 8 personnes et soutire 800 millions est apparu en premier sur .
Categories: Afrique
«Wenn nicht Vernunft einkehrt, droht eine Eskalation»
Mehrere Angriffe auf saudische Flughäfen, zahlreiche Tote und Verletzte: Die Huthi verschärfen den Konflikt mit Saudi-Arabien. Welche Ziele verfolgen sie und wie gross ist die Gefahr einer regionalen Eskalation? Das erklärt Erich Gysling im Podcast «Durchblick».
Categories: Afrique, Swiss News
Das sind die schnellsten Tore in Europas Top-Ligen
Augsburg-Profi Robin Fellhauer erzielt am Samstag gegen die Bayern das früheste Tor der Bundesliga-Geschichte. In den anderen Top-Fünf-Ligen gings noch schneller – ein Überblick.
Categories: Afrique, Swiss News
Superman zeigt versehentlich sein bestes Stück
Tom Welling postet ein harmloses New-York-Foto. Dabei zeigt der Superman-Star deutlich mehr, als ihm lieb ist.
Categories: Afrique, Swiss News
Chasing the trillions: what MDB lending can - and cannot - mobilise
This paper examines how additional private financial resources can be mobilised through the use of multilateral development bank (MDB) funds. It focuses on identifying the leverage potential of different financing instruments, improving their mobilisation efficiency, and examining how greater leverage can promote development outcomes while safeguarding the financial sustainability of MDBs. Its contribution is a comparative synthesis that brings together mobilisation mechanisms, differences in the public resources and risks underlying leverage ratios, and development impact. The analysis covers six categories: debt instruments, equity instruments, risk-transfer instruments, guarantees, advisory services and policy-based lending. It compares their characteristics, including the level of intervention, mobilisation mechanisms, constraints addressed and time horizons. It also distinguishes transaction-level private direct and indirect mobilisation from broader catalytic effects arising through market development, institutional strengthening and policy reforms.
The comparison shows why instruments cannot be assessed by a single leverage ratio. MDB lending, guarantee exposure and expenditure on advisory services represent different commitments of public resources and risk. Similarly, private finance linked to a transaction cannot be measured in the same way as subsequent investment enabled by policy reform. Available evidence therefore indicates differences in mobilisation potential rather than an established empirical ranking of instruments. The paper argues that leveraging efficiency can be increased by moving to more powerful approaches and by better targeting instruments to binding investment constraints. It examines how this can enhance the development impact and financial viability of MDB/DFI portfolios through two channels: a financial/portfolio efficiency channel and a development/catalytic channel. However, a high leverage ratio does not necessarily indicate superior performance. It may reflect investment in easier markets, weak additionality or an understatement of public risk. Conversely, a lower ratio may be consistent with greater additionality in a fragile market or pioneering sector. These findings highlight the importance of assessing leverage alongside additionality, development impact and financial sustainability. Using concessional funds through blended finance instruments can be costly and can reduce the resources available for other development priorities.
Therefore, the development finance institutions (DFIs) must strictly apply the additionality principle and further operationalise the principle of using minimum concessionality. If interpreted too generously, there is a risk of creating leverage without sufficient development impact. The paper provides specific recommendations for refining the use of financing instruments and integrating transaction-level support into a broader market-shaping approach that draws on the strengths of policy-based lending and technical assistance. Higher leverage should not be pursued as an end in itself; its value depends on its contribution to additional development impact.
Dr Jürgen Karl Zattler is a distinguished non-resident fellow at the Center for Global Development in Washington, DC and a non-resident research fellow at the German Institute of Development and Sustainability (IDOS) in Bonn. Until October 2023, he was Director General at the German Ministry for Economic Cooperation and Development (BMZ). Prior to that, he served as the Executive Director representing Germany at the World Bank.
Categories: Diplomacy & Defense Think Tank News, Union européenne
Chasing the trillions: what MDB lending can - and cannot - mobilise
This paper examines how additional private financial resources can be mobilised through the use of multilateral development bank (MDB) funds. It focuses on identifying the leverage potential of different financing instruments, improving their mobilisation efficiency, and examining how greater leverage can promote development outcomes while safeguarding the financial sustainability of MDBs. Its contribution is a comparative synthesis that brings together mobilisation mechanisms, differences in the public resources and risks underlying leverage ratios, and development impact. The analysis covers six categories: debt instruments, equity instruments, risk-transfer instruments, guarantees, advisory services and policy-based lending. It compares their characteristics, including the level of intervention, mobilisation mechanisms, constraints addressed and time horizons. It also distinguishes transaction-level private direct and indirect mobilisation from broader catalytic effects arising through market development, institutional strengthening and policy reforms.
The comparison shows why instruments cannot be assessed by a single leverage ratio. MDB lending, guarantee exposure and expenditure on advisory services represent different commitments of public resources and risk. Similarly, private finance linked to a transaction cannot be measured in the same way as subsequent investment enabled by policy reform. Available evidence therefore indicates differences in mobilisation potential rather than an established empirical ranking of instruments. The paper argues that leveraging efficiency can be increased by moving to more powerful approaches and by better targeting instruments to binding investment constraints. It examines how this can enhance the development impact and financial viability of MDB/DFI portfolios through two channels: a financial/portfolio efficiency channel and a development/catalytic channel. However, a high leverage ratio does not necessarily indicate superior performance. It may reflect investment in easier markets, weak additionality or an understatement of public risk. Conversely, a lower ratio may be consistent with greater additionality in a fragile market or pioneering sector. These findings highlight the importance of assessing leverage alongside additionality, development impact and financial sustainability. Using concessional funds through blended finance instruments can be costly and can reduce the resources available for other development priorities.
Therefore, the development finance institutions (DFIs) must strictly apply the additionality principle and further operationalise the principle of using minimum concessionality. If interpreted too generously, there is a risk of creating leverage without sufficient development impact. The paper provides specific recommendations for refining the use of financing instruments and integrating transaction-level support into a broader market-shaping approach that draws on the strengths of policy-based lending and technical assistance. Higher leverage should not be pursued as an end in itself; its value depends on its contribution to additional development impact.
Dr Jürgen Karl Zattler is a distinguished non-resident fellow at the Center for Global Development in Washington, DC and a non-resident research fellow at the German Institute of Development and Sustainability (IDOS) in Bonn. Until October 2023, he was Director General at the German Ministry for Economic Cooperation and Development (BMZ). Prior to that, he served as the Executive Director representing Germany at the World Bank.
Categories: Diplomacy & Defense Think Tank News, European Union
KI ignoriert vier von zehn Schweizer Geschäften
KI wird bei der Suche nach Bäckereien, Coiffeuren oder Automechs immer wichtiger. Eine neue Studie liefert für Gewerbler aber ernüchternde Zahlen: Viele Betriebe tauchen in KI-Antworten gar nicht auf. Der Gewerbeverband beschwichtigt.
Categories: Afrique, Swiss News
Kronprinzessin Leonor verliert ihren Orden
Patzer vor grossem Publikum: Kronprinzessin Leonor verlor bei der Militärparade zum spanischen Nationalfeiertag in Madrid ihr Goldenes Vlies – und rettete die Insignie mithilfe ihrer Eltern.
Categories: Biztonságpolitika, Swiss News
Kronprinzessin Leonor verliert ihren Orden
Patzer vor grossem Publikum: Kronprinzessin Leonor verlor bei der Militärparade zum spanischen Nationalfeiertag in Madrid ihr Goldenes Vlies – und rettete die Insignie mithilfe ihrer Eltern.
Categories: Afrique, Swiss News
König Felipe hilft Prinzessin Leonor bei Missgeschick
Madrid feiert am 12. Oktober den Nationalfeiertag. Im Fokus steht Kronprinzessin Leonor, der vor Hunderttausenden ein Missgeschick passiert.
Categories: Afrique, Swiss News
Schreckt die «Theorie des Sieges» Putin ab?
Nato-Oberbefehlshaber Alexus Grynkewich hat am Montag in Polen eine deutliche Warnung Richtung Kreml geschickt. Er stellte seine sogenannte «Theorie des Sieges» vor, die Putin vor einem Angriff auf Nato-Gebiet abschrecken soll.
Categories: Afrique, Swiss News
Das Männertennis bekommt neue Nummer eins
Das Herrentennis hat eine neue Nummer eins – zumindest bald. Nach Carlos Alcaraz' überraschender Niederlage in Shanghai ist Alexander Zverev der Sprung an die Spitze nicht mehr zu nehmen.
Categories: Europäische Union, Swiss News
Enseignement primaire : ce qui change pour la langue arabe et les mathématiques (ministère)
Le ministère de l’Éducation nationale a décidé de réorganiser la semaine d’intégration pour les matières de langue arabe et de mathématiques au niveau de l’enseignement […]
L’article Enseignement primaire : ce qui change pour la langue arabe et les mathématiques (ministère) est apparu en premier sur .
Categories: Afrique
5 technologies qui transforment les humains en demi-machines
Voler dans l'espace est depuis longtemps un rêve humain, du mythe grec d'Icare aux voitures volantes des films de science-fiction comme Blade Runner.
Categories: Afrique, European Union
Des localités d'Adjohoun affectées par les inondations
La montée des eaux du fleuve Ouémé affecte plusieurs localités de la commune d'Adjohoun, dans le département de l'Ouémé. À Gangban, Togbota, Dannou et Gogbo, les inondations touchent les habitations et les terres agricoles et les activités scolaires sont perturbées.
La crue du fleuve Ouémé perturbe les conditions de vie des populations de Gangban, Togbota, Dannou et Gogbo, dans la commune d'Adjohoun. La montée des eaux entraîne la submersion de terres agricoles et encercle des habitations.
La situation affecte aussi les activités économiques des populations, dont une partie dépend de l'agriculture. Face aux difficultés rencontrées, les habitants appellent les autorités à intervenir pour leur apporter une assistance.
Le secteur de l'éducation est aussi touché. À l'École primaire publique (EPP) de Dannou, dans l'arrondissement de Gangban, les cours sont interrompus.
La crue du fleuve Ouémé est un phénomène saisonnier qui survient généralement entre août et novembre au Bénin. Elle est liée aux précipitations dans le bassin du fleuve, notamment dans le nord et le centre du pays, ainsi qu'aux pluies enregistrées dans le sud. La montée des eaux entraîne régulièrement des inondations dans les communes de la vallée et du delta de l'Ouémé, notamment Dangbo, Adjohoun, Bonou, les Aguégués et Zagnanado, avec des conséquences sur les habitations, les cultures et le bétail.
Début octobre, le maire d'Adjohoun, Félicien Hounkanrin, a appelé les populations à redoubler de vigilance face à la montée des eaux.
Double Chance : les numéros gagnants
LES RÉSULTATS DOUBLE CHANCE SONT LÀ !
LOTO FORTUNE Tirage N°163/26
Lundi 12 Octobre 2026 (14H)
– Zone A (5 premiers numéros) :
49 • 06 • 56 •30 • 42
– Zone B (5 derniers numéros) :
67 • 69 • 58 • 51 • 09
Félicitations aux heureux gagnants.
Pas encore cette fois ? Gardez le sourire !
Rendez-vous à 18H pour le prochain tirage.
Jouez avec modération et responsabilité. Le jeu doit rester un plaisir.
A TOI DE JOUER #Akaxòa
#LNBSA #XòGbɔnAlɔkpaVo #JeuResponsable #LaChanceAvecModération
Pages
the old site is here

© 2012-2015 Europa Varietas Foundation © 2015-2020 Europa Varietas Association
www.europavarietas.org | info(@)europavarietas(dot)org | Switzerland
This is a GDPR ready site
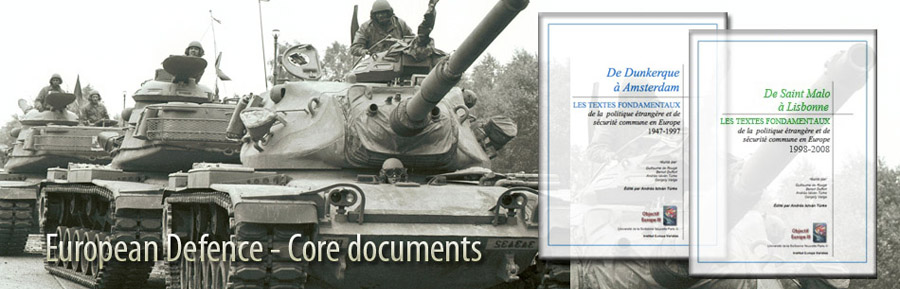
We are looking for sponsors for the English translation of these books, please contact turkeandras(at)gmail(dot)com